• Home
  • Get A Quote
  • Customer Service
  • Refer a Friend
  • About Us
  • Location Map
  • Employee Directory
  • Privacy Policy
  • Contact Us
Call Us CALL US | (803) 430-9002
Home
  • Inicio
  • Productos
    • Automóvil
    • Negocios y Comercio
    • Bonos
    • Seguro para contratistas
    • Seguro de Discapacidad
    • Inundación
    • Salud
    • Propietarios
    • Vida
    • Motocicleta
    • Vehículos recreativos
    • Inquilinos
    • Fianza de Fianza
    • Transporte por carretera
  • Pide un presupuesto
    • Formularios de presupuesto de seguro de cocheImage of right arrow
      • Presupuesto conjunto de seguro de coche y hogar
      • Presupuesto instantáneo de seguro de coche
    • Formulario de solicitud de fianza
    • Formularios de cotización de seguros empresariales y comercialesImage of right arrow
      • Presupuesto de seguro de automóvil comercial
      • Formulario de Presupuesto de Responsabilidad Civil General
    • Formulario de presupuesto para contratistas
    • Formulario de Cotización por Inundación
    • Formularios de presupuesto de seguro médico
    • Presupuesto de seguro de discapacidad
    • Formularios de presupuesto de seguro de hogarImage of right arrow
      • ¡Obtén un presupuesto instantáneo de hogar y coche ahora!
      • ¡Obtén un presupuesto instantáneo para propietarios ahora!
    • Formularios de cotización de seguro de vidaImage of right arrow
      • Consigue ahora un presupuesto de vida instantánea
      • ¿Cuánto seguro de vida necesitas
    • Presupuesto de seguro de motocicleta
    • Formulario de cotización de seguro recreativo
    • Presupuesto de seguro para inquilinos
    • Fianzas
    • Transporte por carretera
  • Blog
  • Recursos
    • Centro de Información de Seguros
    • Último boletín de Home & Auto
    • Último boletín de Commecial
    • Lista de verificación de revisión de seguros de 21 puntos
    • Solicitar revisión de la política
    • Haz un pago
    • Solicita una tarjeta de identificación automática
    • Solicitar un certificado
    • Recomienda a un amigo o familiar
    • Glosario de seguros
  • Sobre nosotros
    • Sobre nosotros
    • Ubicación(es)
    • Directorio de empleados
    • Testimonios
    • Política de privacidad
  • Contacto
Auto Insurance AUTO

Auto insurance protects you against financial loss if you have an accident.

Read More
Homeowners Insurance HOME

A standard policy insures the home itself and the things you keep in it.

Read More
Business Insurance BUSINESS

Discover the perfect insurance options to meet your specific and unique needs.

Read More
Contractors Insurance CONTRACTORS

Learn about different health coverage options that fit your specific needs.

Read More
Recreational Insurance RECREATIONAL

Finding insurance doesn't have to be difficult. We do the work for you.

Read More
Life Insurance LIFE

Browse a variety of insurance options in order to find the right one for you.

Read More
Home > Es-Us > Blog > Why Insurance Rates Go Up When You Total Your Car
MONDAY, NOVEMBER 2, 2026

Why Insurance Rates Go Up When You Total Your Car

Having a car wreck means considering whether your auto insurance will cover the costs of vehicle repairs. Sometimes, your insurer might actually opt to declare your car a total loss, rather than paying to repair it. When they total the vehicle, they will reach a settlement with you for the value of the car, based on the terms of your policy.

However, totaling your car might cause your auto insurance rates to rise, and this is a financial ramification that many people don’t expect. Still, it’s not something that is means to overwhelm you. Here’s why it might happen to you.

What Caused the Car Accident? silver and black car engine
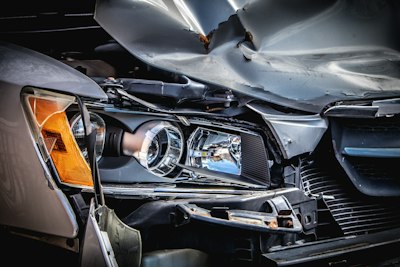
When you have a major accident, then your auto insurer is going to want to know why. After all, they are the ones who are going to have to pay for the accident damage.

Some accidents are beyond your control. You might be rear-ended while at a stoplight, for example. Under the circumstances, you were obeying the law, and it was the other driver who ran into you. Therefore, the fault lies with them.

However, if you were to rear-end another vehicle because you didn’t stop in time, then you will be at-fault for the accident. At this time, because you cause the wreck that damaged both your car and someone else’s property, then your insurer is likely to have to bear the brunt of the recovery costs. Therefore, they are going to likely view you as a high-risk driver.

Because they consider that you have a higher likelihood of having an accident behind the wheel, your insurer will likely have to raise your premiums. The more likely you are to file a claim, the more you are going to cost the insurer. After all, if you total cars frequently, that puts the insurer on the line for thousands of dollars’ worth of settlement costs. Therefore, they simply must make up this cost risk.

Will Rates Increase for No-Fault Accidents?

Just because an accident was not your fault, that does not mean that you are free from rate increases.

For example, if you get hit by an uninsured driver, then you might be forced to file a total loss claim against your own uninsured/underinsured motorist coverage. As a result, your insurer will be the party that has to pay the settlement to replace your vehicle. Therefore, some will have to raise your rates because you relied on them to pay for your new vehicle. That is still a cost-risk even though it was not related to an accident that was your fault.

However, not all insurers penalize drivers who file uninsured/underinsured motorist claims, simply because they do not penalize driver who had no contributing fault in the accident. Therefore, if you ever need to file a claim for such damage, simply speak to your agent. They can help you determine what, if any, financial ramifications you might face.

Posted 1:04 PM

Tags: auto insurance
Share |


No Comments


Post a Comment
Required
Required (Not Displayed)
Required


All comments are moderated and stripped of HTML.

NOTICE: This blog and website are made available by the publisher for educational and informational purposes only. It is not be used as a substitute for competent insurance, legal, or tax advice from a licensed professional in your state. By using this blog site you understand that there is no broker client relationship between you and the blog and website publisher.
Blog Archive
  • 2026
  • 2025
  • 2024
  • 2023
  • 2022
  • 2021
  • 2020
  • 2019
  • 2018
  • 2017
  • 2016
  • 2015
  • 2014
  • 2012

  • affordable insurance group(52)
  • auto insurance(50)
  • insurance(43)
  • home insurance(36)
  • coverage(24)
  • car insurance(16)
  • protection(11)
  • tips(9)
  • life insurance(8)
  • home(7)
  • life(7)
  • business insurance(7)
  • winter(6)
  • claims(6)
  • homeowners insurance(6)
  • homeowner(6)
  • loss(4)
  • weather(4)
  • flood insurance(4)
  • safety(4)
  • sr-22 insurance(4)
  • policy(4)
  • rv insurance(3)
  • boat insurance(3)
  • repairs(3)
  • risk(3)
  • bonds(2)
  • bop insurance(2)
  • renters insurance(2)
  • options(2)
  • motorcycle insurance(2)
  • finances(2)
  • quote(2)
  • construction(2)
  • auto(2)
  • claim(2)
  • accident(2)
  • exclusions(2)
  • contractors insurance(2)
  • theft(2)
  • damage(2)
  • women(1)
  • prevention(1)
  • gaming systems(1)
  • autonomous vehicles(1)
  • home insurance exclusions(1)
  • transmission(1)
  • fraud(1)
  • loans(1)
  • requirements(1)

View Mobile Version
Facebook
Twitter
LinkedIn
Yelp
ASI Homeowners of America National General Progressive Stillwater The Hartford The Main Street Travelers Zurich

Resources

Home About Us Get a Quote Make A Payment Newsletter Refer A Friend Contact Us

Contact Us

Affordable Insurance Group
  • Affordable Insurance Group
  • 6168 Saint Andrews Road
  • Columbia, SC 29212
  • O:(803) 430-9002
  • F:(803) 798-5100
  • E: info@affordableinsgrp.com
© Copyright 2020. All rights reserved.
Powered by Insurance Website Builder